Chatham Hills Market Update: Westfield, IN Luxury Real Estate Trends – August 2026Chatham Hills continues to set the pace for luxury real estate in Westfield, IN. Based on 76 recent

Dated: December 9 2025
Views: 92

If you’re like a lot of homeowners, you’ve probably thought: “I’d like to move… but I don’t want to give up my 3% rate.” That’s fair. That rate has been one of your best financial wins – and it can be hard to let go. But here’s what you need to remember...
A great rate won’t make up for a home that no longer works for you. Life changes, and sometimes, your home needs to change with it. And you’re not the only one making that choice.
Many homeowners have been frozen in place by something the experts call the lock-in effect. That's when you won't move because you don’t want to take on a higher rate on your next home loan. But data from Federal Housing Finance Agency (FHFA) shows the lock-in effect is slowly starting to ease for some people.
The share of homeowners with a mortgage rate below 3% (the yellow in the graph below) is slowly declining as more people move. And while some of the people with a rate over 6% are first-time buyers, the number of homeowners with a rate above 6% (the blue) is rising as others take on higher rates for their next home:
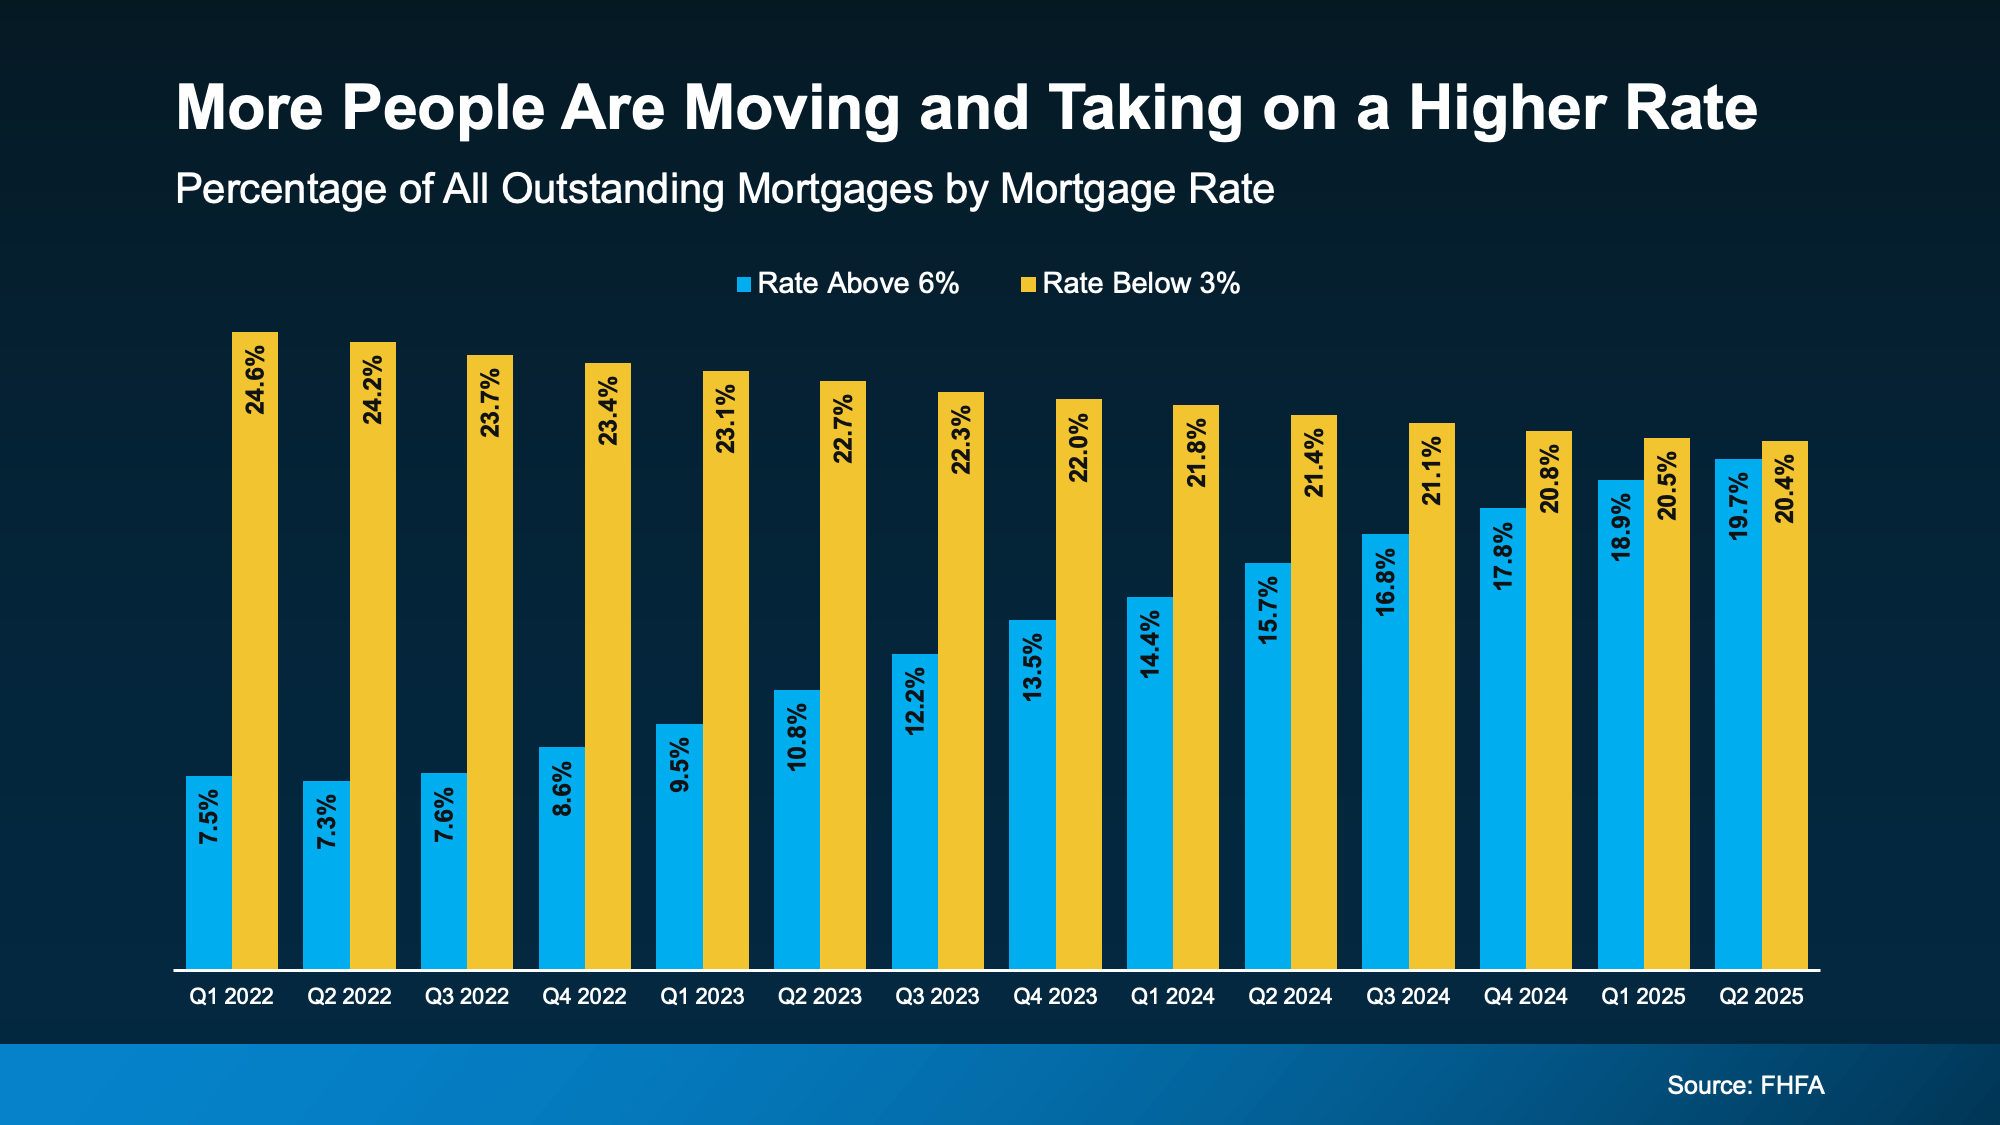
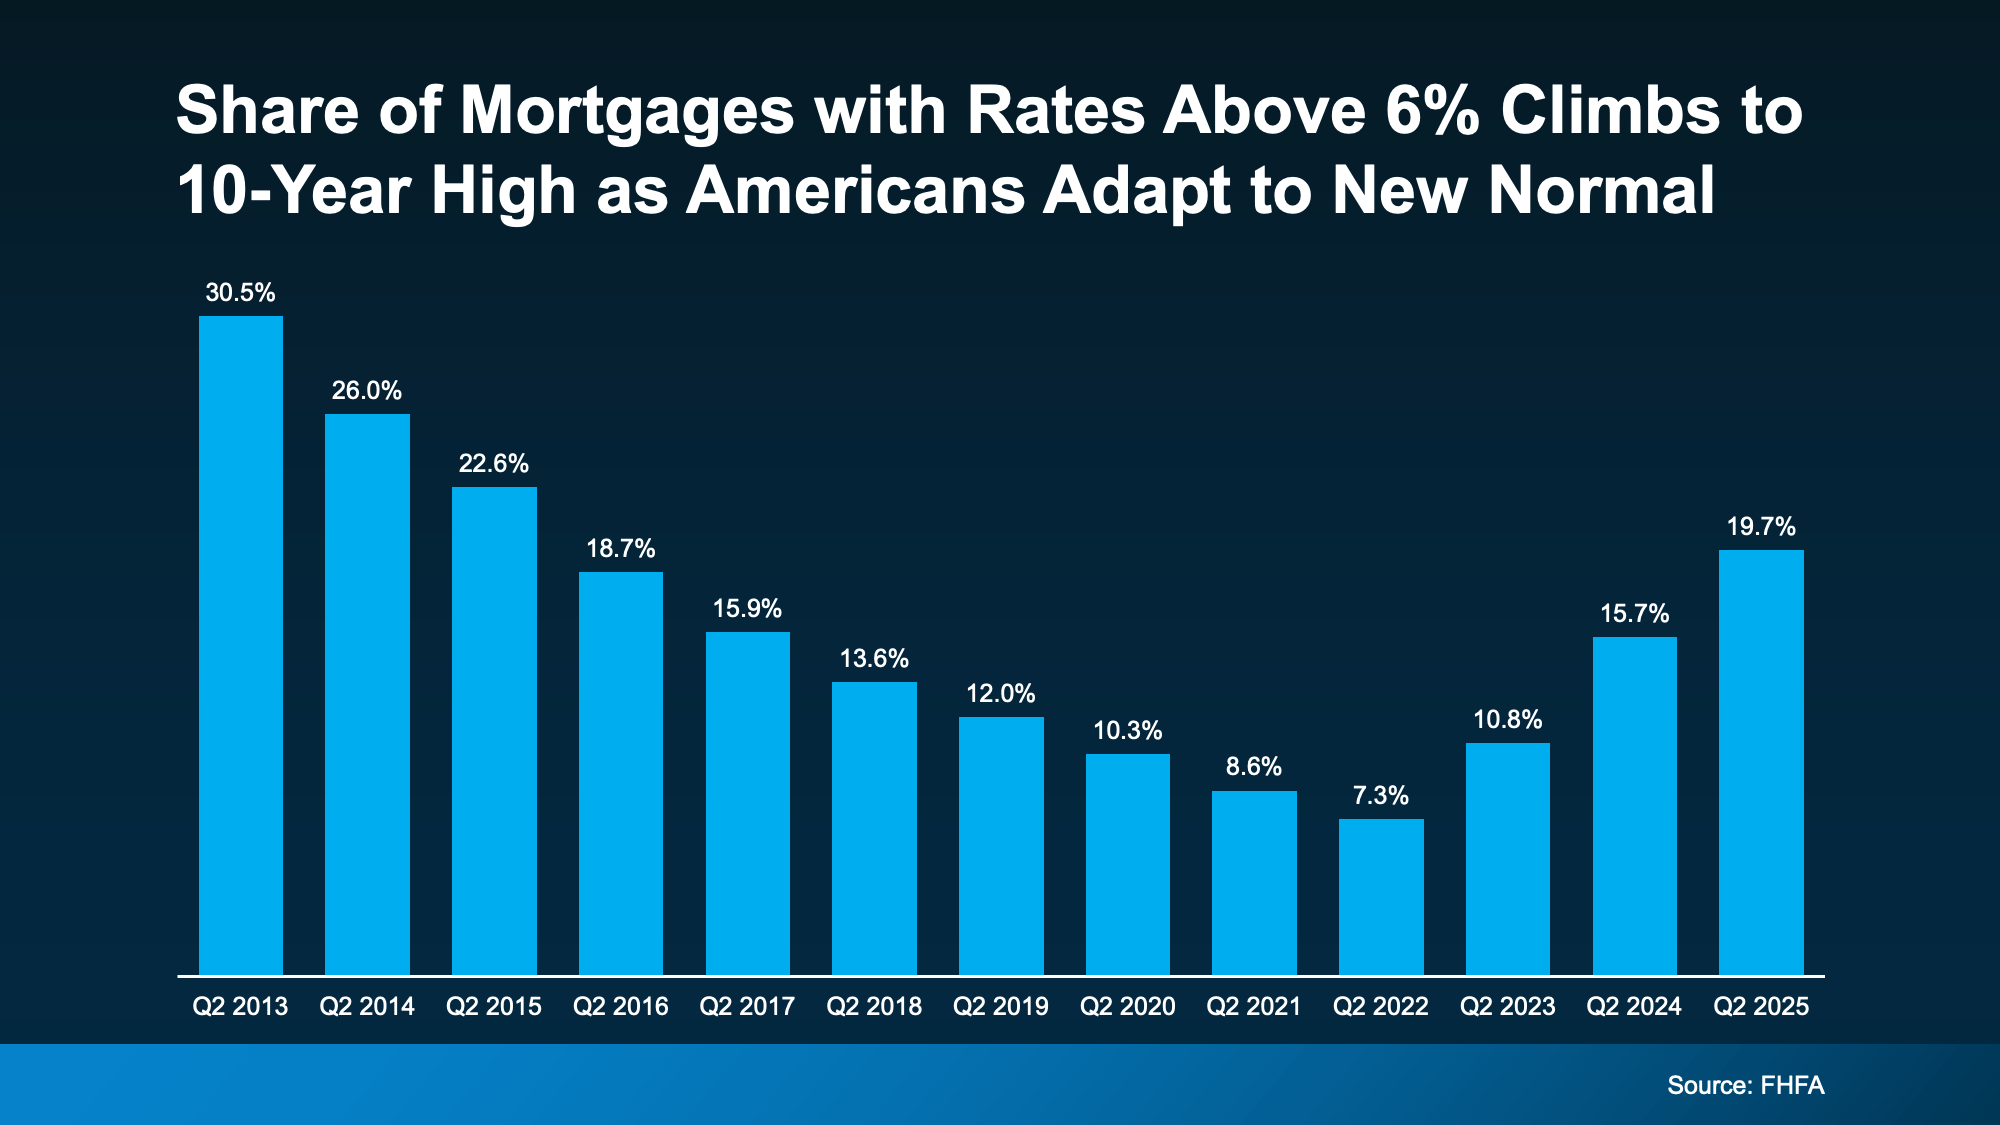
And while it may not seem that dramatic, it’s actually a pretty noteworthy shift. The share of mortgages with a rate above 6% just hit a 10-year high (see graph below). That shows more people are getting used to today’s rates as the new normal.
 Why Are More People Moving Now, if It Means Taking on a Higher Rate?
It’s simple. Sometimes they can’t put their life on pause anymore. Families grow, jobs change, priorities shift, and a house that once fit perfectly may not fit at all anymore – no matter how good their rate was. And that’s okay. As Chen Zhao, Head of Economic Research at Redfin, explains:
“More homeowners are deciding it’s worth moving even if it means giving up a lower mortgage rate. Life doesn’t standstill—people get new jobs, grow their families, downsize after retirement, or simply want to live in a different neighborhood. Those needs are starting to outweigh the financial benefit of clinging to a rock-bottom mortgage rate.”
First American refers to these life motivators as the 5 Ds:
Whatever your reason, here’s what you need to think about. Yes, your low rate is great. But staying put means your life may stay on hold. And maybe that’s not working for you anymore.
According to Realtor.com, nearly 2 in 3 potential sellers have already been thinking about moving for over a year. That’s a long time to press pause on your plans. On your needs. On your family’s goals. So, maybe the question isn’t: “Should I move?”
It’s actually: “How much longer am I willing to stay somewhere that no longer fits my life?”
Because we’ve already seen rates come down from their peak earlier this year. And they're expected to ease a bit more in 2026. When you stack that on top of the very real reasons you may need a new home, it may be enough to finally move the needle for you.
Life doesn’t wait for the perfect rate. Maybe you shouldn’t either.
With mortgage rates down from their peak and forecast to dip slightly more in 2026, moving may be more feasible than you think. If you’re ready to see what’s possible in our market, let’s talk.
In the world of Real Estate, there are those who simply facilitate transactions, and then there are those who go above and beyond to make a profound impact on the lives of their clients. Meet Jason Ju....
Chatham Hills Market Update: Westfield, IN Luxury Real Estate Trends – August 2026Chatham Hills continues to set the pace for luxury real estate in Westfield, IN. Based on 76 recent
If you're watching the housing market in Carmel, Westfield, Zionsville, or Noblesville, Indiana, the numbers are in for June 2026 — and they tell a clear story: this remains one of the,
If you've been thinking about selling in Westfield, IN | Carmel, IN | Noblesville,IN | Zionsville, IN, you've probably seen plenty of headlines suggesting buyers have just about disappeared. But
Let me ask you something, and I want you to sit with it for a second before you answer.Think about the people you’re in business with right now. Your broker. The agents in your office. The
Additional:
600 E. Carmel Drive Suite 270Should you require assistance in navigating our website or searching for real estate, please contact our offices at 888-611-3912.

 MIBOR REALTOR® Association All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than eXp Realty in Metropolitan Indianapolis may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 23, 2026 12:53 PM UTC
33. Required DMCA Notice
The Digital Millennium Copyright Act of 1998, 17 U.S.C. §512, the DMCA, provides recourse for copyright owners who believe that material appearing on the Internet infringes their rights under U.S. copyright law. If you believe in good faith that any content or material made available in connection with our website or services infringes your copyright, you (or your agent) may send us a notice requesting that the content or material be removed, or access to it blocked. Notices must be sent in writing by email to DMCAnotice@MLSGrid.com. The DMCA requires that your notice of alleged copyright infringement include the following information: (1) description of the copyrighted work that is the subject of claimed infringement; (2) description of the alleged infringing content and information sufficient to permit us to locate the content; (3) contact information for you, including your address, telephone number and email address; (4) a statement by you that you have a good faith belief that the content in the manner complained of is not authorized by the copyright owner, or its agent, or by the operation of any law; (5) a statement by you, signed under penalty of perjury, that the information in the notification is accurate and that you have the authority to enforce the copyrights that are claimed to be infringed; and (6) a physical or electronic signature of the copyright owner or a person authorized to act on the copyright owners behalf. Failure to include all of the above information may result in the delay of the processing of your complaint.
